
-
 Bank Ranking
Banks Ratios
Cement Statistics
Cement Ranking
Cement Ratios
Monetary and Economic Statistics
Oil, Gas and Fuel
Macro Economy
Consumer Spending
Inflation
Exports & Imports
Food Prices
Non Food Prices
Construction Materials
Petrochem. Ranking
Petrochem. Ratios
Retail Rankings
Retail Ratios
Grocery Ranking
Grocery Ratios
Top Growth
Dividend History

New Saudi IPO rules to boost market appeal or raise listing costs?

 AI Summary

Content Summary: 
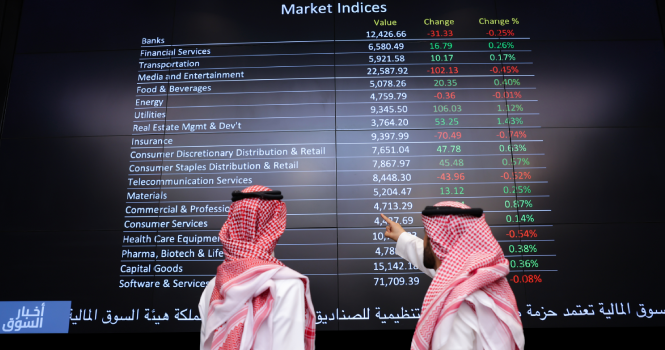
Tadawul trading screen
Saudi Arabia’s Capital Market Authority (CMA) has approved regulatory provisions under its initiative to improve IPO practices, strengthening underwriters’ responsibilities, tightening investor financial solvency verification requirements during book-building, and mandates the disclosure of future financial forecasts.
Coming at a time when Saudi IPO activity has experienced a significant slowdown—dropping to just 3 offerings in the Main Market (TASI) and the Nomu-Parallel Market during the first eight months of 2026 compared to 29 in the same period last year, Argaam surveyed senior executives at leading financial institutions to evaluate the regulatory changes, their impact on stakeholders, and potential implementation hurdles.
While participants unanimously agreed that the amendments improve offering discipline and disclosure quality, opinions diverged regarding their impact on listing costs, corporate valuations, institutional appetite, and underwriter liability.
New mechanisms tackle underwriter risk management
Omar Al Kathiri, Head of Investment Banking at Value Capital, noted that permitting pre-agreed disposal mechanisms for shares in the event of a failed listing is one of the most mature elements of the new rules. It transforms an ambiguous scenario into a pre-approved framework, mitigating disputes between issuers, selling shareholders, and underwriters.
Omar Al Kathiri, Head of Investment Banking at Value Capital
Mohamed Al-Sayyed, Chairman and CEO of Amwal Financial, explained that underwriter obligations apply strictly to main market equity offerings rather than Nomu listings, private placements, or debt instruments. Under the rules implemented on Nov. 2, the underwriting agreement must take effect prior to book-building, binding the underwriter to purchase the full offering even if it breaches listing requirements.
Mohamed Al-Sayyed, Chairman and CEO of Amwal Financial
While this provides issuers with execution certainty, El-Sayed expects it to prompt stricter due diligence, conservative pricing, and more rigorous contractual terms, alongside liquidity and capital adequacy risks for underwriters who may need to offload unlisted shares.
Meanwhile, Ghassan AlThukair, CEO and Managing Director of Miyar Capital, said the provision addresses one of the key risks facing underwriters: having capital tied up while bearing the risk of holding unlisted shares, noting that an underwriting commitment could effectively become an investment decision if a listing fails.
Ghassan AlThukair, CEO of Miyar Capital
Such a predefined exit strategy converts the underwriting commitment into a manageable investment decision, helping institutions price risk more accurately and potentially lowering risk premiums if strong demand exists, he explained.
Potential exit mechanisms include selling shares to qualified or strategic investors, redistributing them through a private placement, or gradually selling them under clear controls. Another option is to enter into prior agreements with other parties to purchase the shares if the listing fails, provided such arrangements comply with regulatory requirements.
AlThukair stressed the importance of defining these mechanisms when the underwriting agreement is signed, rather than addressing exit risks after a problem arises.
Would underwriting fees rise and financial institutions’ appetite wane?
Al Kathiri suggested that longer exposure periods could drive limited fee repricing to match increased capital burdens, though clear exit mechanisms and disciplined orders will keep pricing tied to offering quality. He anticipates that well-capitalized institutions will maintain their appetite, increasingly relying on syndicates.
Book-building controls also reduce underwriters’ actual risk by requiring investor orders to reflect available liquidity, limiting solvency verification to cash and cash equivalents, and treating orders placed at a specific price as covering all lower price levels. Orders must also be supported by the investor’s ability to pay.
These controls curb inflated demand and make book-building results a more accurate indicator of the market’s capacity to absorb an offering, he added.
Al Kathiri expects limited repricing of underwriting fees in some offerings, reflecting the extended commitment period and greater capital burden under capital adequacy rules. However, clear disposal mechanisms and more disciplined demand should limit this impact, making pricing more closely tied to each offering’s quality and strength.
He also expects well-capitalized financial institutions to maintain their appetite for underwriting, alongside greater reliance on underwriting syndicates and more disciplined pricing ranges, ultimately benefiting both issuers and investors.
Conversely, El-Sayed warned that heightened risks could dampen the appetite of licensed financial institutions—particularly foreign players—leading to greater selectivity and higher underwriting fees.
From another perspective, AlThukair expects the share disposal mechanism in the event of a failed listing to mitigate some financial risks but not eliminate them entirely. Underwriters will remain obligated to purchase all offered shares, which could subsequently lose value, prove difficult to liquidate or require an extended holding period.
However, ownership of these shares could also generate investment returns, he noted.
A clearly defined exit mechanism reduces uncertainty and enables financial institutions to assess their risk exposure and determine the required capital allocation, potentially lowering risk premiums and underwriting costs for issuers, depending on the mechanism’s effectiveness, actual demand for the shares and the underwriter’s investment decision.
He expects the amendment to encourage more institutions to participate in underwriting, particularly those previously reluctant to take part in certain offerings because of the risk of a failed listing.
Al-Thukair stressed the need to balance stronger underwriter responsibilities with practical risk management tools, particularly as making underwriting commitments binding from the start of book-building increases underwriters’ risk exposure.
Such a balance would help preserve competition in the underwriting market and prevent the activity from becoming concentrated among a limited number of financial institutions.
Extended horizons for financial forecasts: longer
AlThukair said the new rules tie forecast periods to the remaining duration of the financial period included in the prospectus plus the subsequent full fiscal year, replacing rigid one-year mandates with a dynamic timeline based on the latest available data.
He described that approach as positive, particularly when valuing companies whose growth prospects are a key business driver. But he emphasized accounting for each company’s business model and operating cycles, especially in sectors exposed to commodity prices, economic cycles, long-term contracts and projects, given differences in their ability to forecast financial performance.
Al-Sayyed said the minimum forecast disclosure period is one full fiscal year if the IPO application includes financial statements for a completed year. If the application is based on reviewed financial statements covering less than a full year, the forecast period extends beyond one year to cover the remainder of that fiscal year and the following year.
Elsewhere, Al-Kathiri noted this could require companies to issue forecasts spanning up to 21 months depending on the reporting date, compelling issuers to build more robust financial models and carefully time their offerings.
Transparency vs. legal liability
Making financial forecasts a mandatory component of IPO prospectuses and inspection documents—rather than an optional marketing tool as seen in international markets like the US, Canada, and Hong Kong—introduces potential legal and operational implications, Al-Sayyed said.
While designed to boost investor confidence and offering quality, mandatory forecasts elevate liability risks for issuers and financial advisors—particularly for companies with seasonal revenues, short-term supply contracts, or developing financial planning practices. Consequently, advisors may adopt more conservative valuations and price ranges for volatile or sensitive forecasts to narrow the gap between projected and actual results.
The primary legal concern stems from Article 55 of the Capital Market Law, which allows compensation claims for material misstatements or omissions in a prospectus. Because the regulations provide no explicit safe harbor for forward-looking disclosures, questions remain over how courts will evaluate shortfalls between projected and actual performance.
El-Sayyed noted that this uncertainty could increase advisory costs, prolong IPO preparation timelines, and impact overall listing momentum across both TASI and Nomu.
AlKathiri, meanwhile, expects the disclosure of documented financial forecasts to narrow the information gap between issuers and investors, potentially supporting more attractive company valuations. Investors will be able to assess IPO pricing based on disclosed figures for which the company assumes responsibility.
He explained that the amendments increase financial advisors’ professional accountability by requiring them to exercise due professional care when assessing forecasts, including reviewing and documenting key assumptions and financial modeling methodologies, conducting sensitivity analyses under different scenarios, and ensuring forecasts are consistent with the company’s historical performance and sector conditions.
He argues the expense is offset by improved pricing stability post-listing. He added that issuers must manage liability by disclosing underlying methodologies, assumptions, and risk factors transparently, while maintaining post-listing disclosures for any material deviations.
Regarding the risk of forecasts not materializing, AlKathiri said the potential consequences include an impact on share prices and corporate reputation, as well as possible regulatory and contractual liability if forecasts are found to have been based on unreasonable assumptions.
He stressed the importance of ensuring forecasts are clear and not misleading, with transparent disclosure of the methodologies, assumptions and risks that could cause actual results to differ, while requiring companies to continue reporting any material deviations after listing. He added that conservative and measurable forecasts serve issuers’ interests as much as, if not more than, those of investors.
AlThukair, for his part, expects the amendment to significantly change how IPO candidates are valued by placing greater emphasis on expected future performance alongside historical results and comparisons with peer companies.
He explained that the new disclosures will help investors assess companies' ability to achieve targeted growth, improve profit margins and cash flows, and sustain earnings. This should improve pricing quality and reduce reliance on growth assumptions unsupported by sufficient operational and financial indicators.
He added that financial advisors’ responsibilities will extend beyond preparing prospectuses and presenting company-provided information to reviewing forecasts and their underlying assumptions, verifying their reasonableness and consistency with financial performance and operational and financing plans, and assessing their achievability based on companies’ current and projected capabilities.
AlThukair expects offering costs to rise, particularly for companies lacking advanced financial planning systems and forecasting models, due to the need to develop financial models, conduct sensitivity analyses and scenario assessments, and expand due diligence and verification procedures.
He stressed the importance of distinguishing between natural variances caused by market shifts and misleading forecasts lacking reasonable grounds. Conservative, measurable projections, he noted, serve as a vital tool for long-term price discovery rather than a device to justify inflated IPO valuations.
Instead, they should serve as a practical tool to help investors understand and assess companies and monitor their performance after listing.
Comments {{getCommentCount()}}
Be the first to comment
رد{{comment.DisplayName}} على {{getCommenterName(comment.ParentThreadID)}}
{{comment.DisplayName}}
{{comment.ElapsedTime}}

Comments Analysis: